The carcinisation of fintech
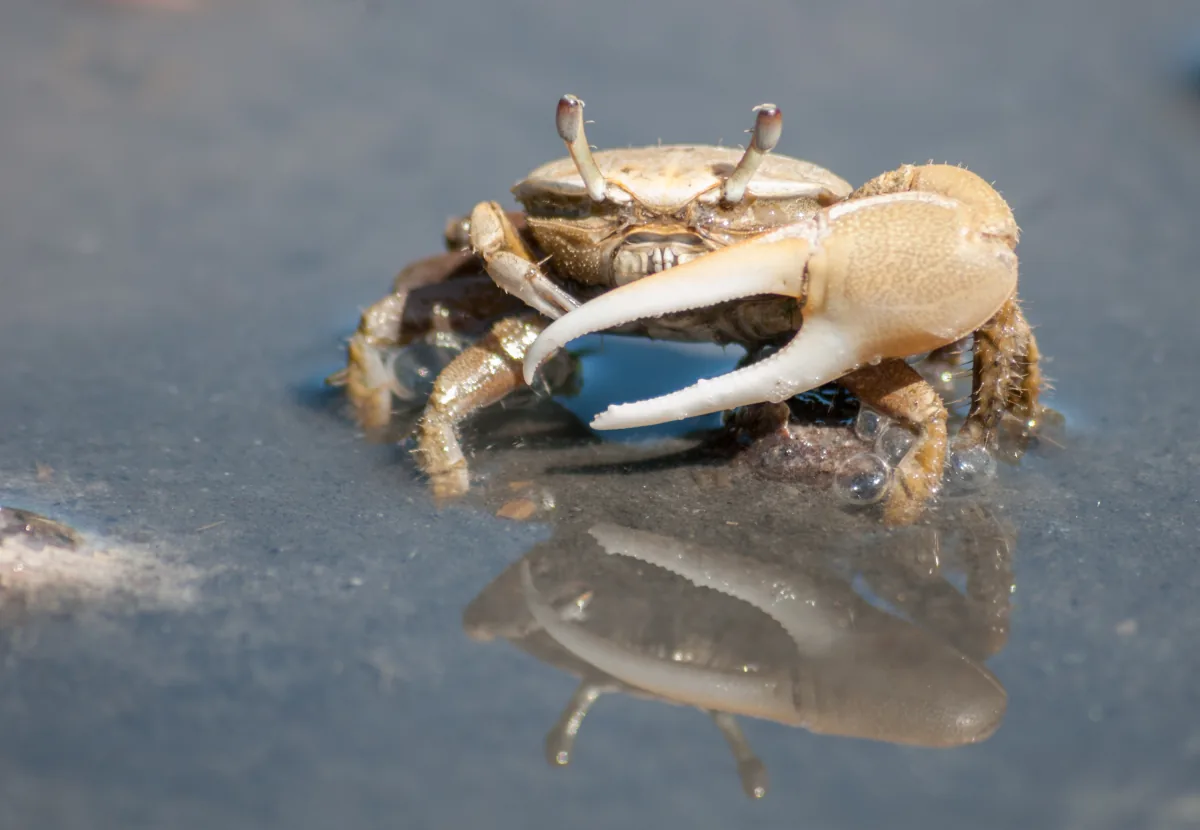
Nature is metal.
Carcinisation is a form of convergent evolution in which crustaceans that aren’t true crabs evolve a crab-like body plan. Or in simpler, less precise terms: animals that are not crabs start looking an awful lot like crabs. One proposed explanation is that the shape helps them survive.
A wide, flattened shell, a broad underside, an abdomen folded up under the body: potentially super useful if you need to squeeze into tiny crevices and keep your soft bits away from hungry predators. King crabs evolved from hermit crab ancestors; porcelain crabs are related to squat lobsters. The coconut crab is another example.
The English zoologist Lancelot Alexander Borradaile gave the phenomenon its name in 1916, calling it one of “the many attempts of Nature to evolve a crab”. A 2021 paper found that the crab-like shape evolved at least five times independently. It has also been lost at least seven times, depending on what worked for the animals in question. Apparently even being crab-shaped isn’t always worth it.
If you hate reading (I’m sorry for you, and what are you doing here!?), there are also videos about it here and here .
The plot twist of this excursion into evolutionary biology is that king crabs, porcelain crabs and coconut crabs aren’t true crabs. They’re on a different branch of the evolutionary tree from true crabs. Their anatomy gives it away: female king crabs, for example, still have an asymmetrical abdomen. It’s a leftover from ancestors that curled up inside spiral snail shells.
And while spending my free time nerding out about random science facts, I realised this is an excellent metaphor for something observable in fintech: companies that started out doing one thing gradually turning into (neo-)banks, or at least looking suspiciously like them.
I now lovingly call it the carcinisation of fintech.
The bank-shaped fintech
What would such a bold hypothesis be without examples? So let’s have them.
Starting with the most obvious of them all – Revolut. Remember what Revolut started as? Surely not as the most successful neobank of the last decade. It was a card for spending abroad without getting robbed by the exchange rate. Since then, it has added accounts, savings, trading, credit and business banking … the list goes on and on. It got its full UK banking licence in 2026 . You can still exchange currencies in the app, but this is dwarfed by the countless things you can now do there.
Trade Republic began as a cheap way to trade stocks. Payment for order flow helped pay for those low fees. It now has a full banking licence, pays interest on cash and offers a debit card and current account.
SoFi began with student-loan refinancing. The name is short for Social Finance , reflecting its original model of alumni funding student loans. It bought a shell … I mean, a bank, and now offers checking, savings, mortgages and investing.
Klarna began with payments at checkout and already had a Swedish banking licence in 2017, so the mere licence isn’t new. But for years, to most people, Klarna was still just a pay-later button – and it remained Klarna’s core business for years after acquiring the licence. Now it has a debit card across Europe . Becoming bank-shaped was a more recent event and was mostly driven by its IPO story.
We can stay in Sweden: Anyfin , founded in 2017, started by refinancing expensive consumer debt. Take a photo of your credit-card bill or loan statement and Anyfin offers to replace the debt on better terms. In 2025 it got a Swedish credit-market company licence , allowing it to take deposits as well as lend. That’s not a full-service bank, but it follows the typical carcinisation pattern, starting with one feature and now slowly expanding into bank-like services. You could say: it’s a crab-in-progress.
Then there’s Chime , which spent years telling customers it was not a bank. Its accounts were provided by partner banks, including Stride Bank. Then, in September 2026, Chime agreed to buy Stride for $590 million. If the deal clears the regulators, the partner bank becomes Chime Bank. It has agreed to buy itself a hard bank shell.
Cash App started with sending money to friends. It now offers cards, direct deposit, savings and loans; Block’s own industrial bank has approval to handle Cash App Borrow.
Robinhood started with commission-free trading (remember that payment for order flow from above?) and now advertises checking and savings alongside the brokerage. Robinhood isn’t a bank – its banking products rely on partner banks. From the app, though, the shape is hard to miss.
Let’s do a few more:
Nubank began with a credit card in Brazil and now offers accounts, loans, investments and a mobile phone plan (this is extremely en vogue right now, and I’ll explain why in a minute).
Grab went from ride-hailing to payments to a digital bank in Singapore (that’s a story worth reading!).
Affirm , another pay-later business, has applied to set up a bank of its own in Nevada. Another work-in-progress crab.
And so on, and so forth. There are probably a few dozen more where this list came from.
Now, could I have grouped all these fintechs a bit better? For sure, but that is not the point. These are not identical businesses, and they are geographically completely diverse. To categorise them by their initial service or today’s product offering doesn’t reinforce my point any better.
The common thread is that they built a direct relationship with consumers, then kept adding the same or very similar things: an account, a card, somewhere to park money, some way to borrow it. Some hold a banking licence, some use partner banks, and others are still trying to get a licence of their own. They are in the process of “becoming crab”.
The one unifying thread they all have, regardless of which service they started with or which services they bundle today, is that they’re all competing for the consumer and consumer attention. None of them got big by being invisible infrastructure. Their brands were built selling directly to consumers, not serving other companies’ customers behind the scenes.
Which leads to the question: why do they keep ending up here?
The evolutionary pressure to become a bank
To stay with the evolutionary metaphor, I can observe three main environmental pressures that basically force consumer-facing fintechs to adopt bank-like shapes. This is by no means an exhaustive list of potential reasons. This is, after all, an essay for my blog, not a master’s thesis. If you can think of more (important) reasons for this evolutionary convergence in business, I’m happy to read them in my DMs or via email.
1. Zoom in: ARPU
Let’s zoom in first on the microscopic view of the user before we zoom out to the macro view of companies as a whole.
Take any product you can think of that was a fintech starter. Revolut’s cheap way to spend abroad? Klarna’s financing of, say, a €120 basket for 14–30 days? Trade Republic’s low-cost stock trades? Cash App letting you split a restaurant bill with friends?
Even with massive scale and user growth, the revenue each user generates for any niche financial service remains small and unpredictable. It has to pay for everything, for the entire support apparatus, fraud, compliance, and all the effort to get that user acquisition funnel going. And then turn that acquired user into a repeat customer, and ideally a heavy user of your app. Then you can hope to turn the individual user profitable.
The product itself – if it is good – is a user magnet if it solves one specific problem, but it’s not necessarily a good whole business.
Once you have the customer, you are immediately tempted to sell them more. Maybe a permanent account to keep a record of their transactions. Somewhere to keep savings. Investments, insurance, a loan. Each additional product gives you another chance to make money from the same relationship rather than buying a new customer. Give it enough time, and your original product might even become a footnote. And that new bundle of products makes you look an awful lot like a bank.
Apart from the economies of scale, it is also – at least in Europe – a licensing topic: an e-money institution cannot take deposits and lend those customer funds as a bank would. You can still offer credit through partners or other financing arrangements. But then you sit as the thinnest possible slice on that value chain and don’t have the same control over the economics as if you controlled the entire chain yourself. A banking licence is not the magical button to fix that, but it explains why so many companies eventually want the licence rather than another feature in the app, sponsored by a third party. You can simply avoid having to share that user-generated income with another, very expensive partner in your ecosystem.
Owning the bank isn’t free: you take on capital requirements and ongoing compliance and operating costs. But at scale, spreading the fixed part of that overhead across millions of users can work out cheaper than continually paying another bank its margin.
2. Zoom out: the sunk cost of a consumer brand
Getting a consumer to recognise your name, then install an app amongst a million others on their phone, then go through onboarding, probably even an ID check, and then top it all off by trusting you with money is – mildly put – bloody expensive. After all that, are you going to see them only when they travel once per year, buy a stock once a month or split a restaurant bill every few weeks? Hell no. Not after sinking all that money to get them (and millions of others) there and to make yourself visible in an oversaturated market.
Sunk cost is a bad reason to do anything. But once the brand and the relationship exist, bought by incredible amounts of cash, the dynamics of offering new services change completely, and not doing it would be insane. Offering a service to someone who already knows you is a fundamentally different proposition from finding a stranger and persuading them to go through a face / ID match via video call. You can pivot your entire business in incremental, small steps and it might not even affect your users’ trust and relationship with you – once established.
Let’s take Chime’s proposed acquisition of Stride Bank as an example. Chime already has the customers and the app. It has the brand recognition. By buying its own partner bank of some seven years, it expects to cut partner-bank fees, lower its funding costs and offer a wider variety of lending products. And pushing these products onto the consumer will be much easier at this point. It is trying to get more value out of a relationship it spent years building. Building with a lot of money.
The consumer brand was the expensive thing all along. Building any starter product in fintech is really not the expensive part, but getting consumers to actually use it is. Once you see that, the parade of fintechs adding accounts and cards and mobile phone plans starts to look a lot less mysterious. Investors don’t like money sinks, and “brand recognition” is such an abstract money sink that desperately wants to materialise a return on investment.
3. Compliance is a weapon (with two sharp edges)
Fintechs – in most cases – are trying (in their early days) to fill an evolutionary niche within the financial services ecosystem. Something that the established financial institutions either ignore or completely neglect. Think spending abroad without punitive FX markups, buying a few shares without hefty dealing fees, or getting a pay-later option directly at checkout instead of applying for a separate credit card.
And very often that requires them to enter into a dangerous symbiosis with a partner that might as well be their main predator (what is it with all the biology metaphors? This is fun. We should do this more often!). How that unfolds can be seen when established banks with a large moat called “compliance” use their leverage to squeeze an incumbent out of the market, or pick them up from the market to internalise that perfectly served niche into their own ecosystem. Or simply make the cost of offering that service extremely high by lobbying to extend compliance responsibilities onto start-ups (same rules for all, etc.).
Sure, most of those rules have been established to protect you and your money as a consumer, but it would be a very dishonest take to say that they are not being used and abused as a power imbalance by established brick-and-mortar banks. This is a hill I will die on, but I am happy to listen to your attempts to change my mind.
It takes years to get a banking licence and a lot of investment in building the teams and systems to keep it up and running. Risk controls, auditors, AML and the regulator at the door that allows you in. It’s a very exclusive club, mind you. Again, building the initial product or software is the easy part, but crossing that moat on that very thin bridge – that is extremely hard. Incumbent banks know all this. In the US, the Bank Policy Institute has publicly opposed applications for limited-purpose trust charters, including Wise’s. Community bankers have argued that letting non-banks use narrower charters without the obligations of a full bank creates an uneven playing field.
There are two ways to read that: it can be a genuine argument about safety or a way to slow down competitors. I’ll let you pick a side.
But once you are in the big boys’ club, oh boy. Can you then turn around and pull up that bridge for others! I repeat myself: copying fintech products as software is extremely easy, as is improving upon existing financial products, and in the age of AI even more so. But if the doorknob at Berghain says you can’t come in tonight, the party will go on without you.
On the other side, compliance as a moat is a double-edged sword. If the crab wants to grow faster than its hard shell allows, it will enter a world of pain. BaFin restricted N26’s customer growth over repeated failures in its financial-crime controls; the limit wasn’t lifted until 2024. The FCA fined Monzo £21 million after its controls failed to keep pace with growth and it opened accounts it had been told not to open. These were real failures. The shell protects you from some competitors, but the regulator, aka the hard shell, can also stop your growth in an instant if you want to outpace it. The protection, luckily, still goes both ways.
Where do we go from here?
Well, wouldn’t that be nice to know? Where will the economic-environmental pressures drive fintech evolution? The million-dollar question. Will we see a massive decarcinisation in our lifetimes? Will owning the entire value chain and maintaining that moat become too expensive for its return? Is the way forward to branch out even more? Or to refocus on something else entirely, powered by the promise of “agentic” something-something? Agentic banking? Where the placement of your money is hyper-optimised by AI?
As with all such questions, they are answered by bets – bets that new start-ups and established players are making. Take phone plans, for example – truly a core banking business, no? I jest. But Nubank , Revolut , Klarna and N26 have all made that bet. It seems to be extremely en vogue to offer them and even combine them with your existing product portfolio (NuCel with preferential savings rates, Revolut with travel and roaming). Telecom infrastructure providers and eSIMs have made adding a phone plan to your app extremely easy. And once you have millions of users and a global brand, adding this through third-party infrastructure to your product bundle becomes an obvious choice. You don’t even have to be a bank to do it. Ask Lidl.
So are we seeing the rise of absolute super-apps, closer to their Asian-market counterparts?
Maybe.
There are a few mountains to climb before that can be a reality, and some of those mountains are there for very, very good reasons. “Data protection” and “cyber security” are not abstract terms, but problems that need to be respected first.
Or will agentic AI actually challenge banks’ ownership of the customer relationship? Could a start-up create a product that allows users to shop with their AI agents at different banks, bank-agnostic, so to speak, and pick the best-value financial service among them for any need? We are not talking about another comparison website, but a machine authorised to actually move your money. Squeeze the margins of any bank or fintech that has crossed the big compliance moat, knowing that some bank margins literally depend on customers leaving money in poorly paying accounts and never shopping around?
Reading transaction data, recommending a loan and moving someone’s savings involve very different permissions and liabilities. It requires you to give AI access to your financial data and authority to act. Today it feels like an insane thought to put that into the hands of a non-deterministic agent, but could someone make it work?
Maybe.
Banks have an incentive to welcome some AI transformation – as long as those AI agents reside within their own ecosystem – within their own crab shell. If it comes from the outside, an agent could become a parasite they cannot adapt fast enough to. The banking licence and balance sheet might remain essential, but the customer relationship becomes meaningless since an agent has moved into that niche. Or banks will (again) find a way to include that into their moat, and the rules of the game remain the same.
Evolution explains how we got here much better than it tells us what comes next.
The old shell, left behind. Photo: Daniel Ramirez / CC BY 2.0
